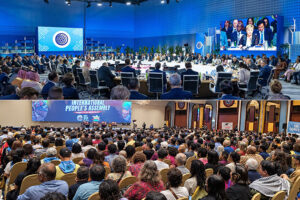
Two parallel economic assemblies met in Bangkok in October 2026: inside the Queen Sirikit Convention Center, finance ministers, central bankers, and International Monetary Fund and World Bank officials managed sovereign debt, price stability, and capital mobilization; outside, social movements and civil society organizations convened the People’s Assembly to challenge austerity, rearmament budgets, and civic erosion. Rather than treating these gatherings as a moral contrast between elite insiders and grassroots outsiders, this analysis separates known facts from structural hypotheses and maps the underlying fiscal mechanics. Developing governments face a trilemma of rising borrowing costs, geopolitical defense spending, and domestic social protection, where decisions made in one track immediately constrain options in the other.
Deconstructing the Bangkok Split
A useful critique of commentary on the Bangkok meetings starts by separating observable events from interpretive framing. Public records confirm that the IMF and World Bank held their 2026 Annual Meetings in Bangkok from October 12 to October 18, 2026, alongside finance minister sessions—including G20 discussions—while civil society groups organized more than 50 parallel sessions outside. Commentary from civil society advocates frames that physical separation as a structural divide between concentrated financial power and affected populations. Institutional leadership frames the same week around global growth projections holding near 3.1%, orderly market functioning, expanded concessional and private capital mobilization, and faster project execution.
Both narratives capture real phenomena while leaving causal links under-specified. Criticisms of austerity often treat fiscal consolidation as a purely ideological choice, whereas institutional reports emphasize debt service burdens, inflation risks, and higher bond yields in leveraged economies. Conversely, official claims of macro stability can understate how debt servicing and external shocks squeeze non-discretionary household budgets in low-income and middle-income countries.
To move past polemics, examine the three core mechanisms linking the inside and outside tracks:
- The Budget Allocation Mechanism: Every unit of public revenue is subject to competing statutory claims, debt service obligations, defense outlays, and social transfers. When external financing becomes costlier or conditional, ministries of finance adjust spending margins where political resistance is weakest or where contracts are short-term.
- The Risk-Pricing Mechanism: Sovereign bond yields and lender terms reflect perceived repayment capacity, inflation trajectories, and geopolitical exposure. Higher risk premia raise rollover costs for indebted governments, tightening domestic fiscal room even before formal adjustment programs are negotiated.
- The Representation Asymmetry: Finance ministries and multilateral boards operate through formal sovereign mandates and balance-sheet metrics, while labor unions, gender advocates, and social movements represent groups whose income or public service access shifts through secondary policy effects.
The Fiscal Squeeze and Policy Trade-Offs
A common question raised by observers of multilateral summits is why governments repeatedly adopt fiscal tightening when social movements warn of hardship. The short answer is balance-sheet constraint rather than a single policy preference. When debt service absorbs a rising share of government revenue amid elevated interest rates or currency pressure, states lose room to finance deficits at acceptable cost. Central banks focused on price stability face pressure to keep monetary conditions tight when inflation risks persist, leaving fiscal authorities with narrower buffers.
Another frequent question concerns how defense and geopolitical tensions affect development budgets. Public commentary on the People’s Assembly highlights rearmament and regional conflicts—spanning Ukraine to the Gulf alongside ongoing crises in the Middle East—as drains on social spending. The causal chain operates through budget competition and supply shocks: security outlays and energy or trade disruptions can raise import bills and fiscal deficits simultaneously, forcing governments to choose between higher debt, tax hikes, or cuts to subsidies, healthcare, education, and care infrastructure.
A third question asks whether mobilizing private capital or streamlining multilateral lending resolves these tensions. Institutional leadership points to faster project preparation, impact-focused scorecards, expanded concessional lending, and higher private capital mobilization as tools to build infrastructure and human capital. This is a plausible partial offset for bankable projects with clear cash flows or risk-sharing structures, but it is not a universal substitute for tax-funded public services such as universal healthcare, social protection floors, or labor enforcement. Private capital generally requires predictable returns and regulatory certainty, whereas redistributive transfers and public administration depend on domestic fiscal capacity.
Evaluating Institutional and Grassroots Claims
Distinguishing verified facts from educated hypotheses prevents overclaiming on either side of the Bangkok debate. Known facts include the timing and location of the October 2026 IMF and World Bank Annual Meetings in Bangkok, the parallel civil society sessions outside, public statements by institutional leaders regarding growth projections, concessional and private capital initiatives, and central bank inflation focus, and civil society priorities covering gender justice, decent jobs, civic space, and demilitarization.
Educated hypotheses involve tracing second-order distributional outcomes where cross-country data lags policy announcements. For instance, it is reasonable to hypothesize that when fiscal consolidation coincides with higher living costs, informal workers and women—who shoulder disproportionate unpaid care responsibilities and rely heavily on public services—experience sharper welfare losses than formal-sector asset holders. It is equally reasonable to hypothesize that if multilateral reforms shorten project timelines without expanding grant and concessional resources for the most vulnerable borrowers, low-income states may still face severe liquidity constraints. Both hypotheses remain contingent on country-level tax collection, debt restructuring terms, and domestic political choices.
In operational practice, policymakers and analysts evaluating stabilization packages routinely run into three recurring blind spots:
- Treating headline aggregate spending as a proxy for household impact: A stable overall budget figure can mask cuts to targeted food, fuel, or care transfers alongside protected capital or security lines.
- Ignoring implementation lag between policy pledges and field delivery: Capital pledges, compacts, and lending targets take quarters or years to translate into clean water, jobs, or wage gains, whereas price shocks and subsidy removals hit households immediately.
- Underestimating political backlash from abrupt adjustment: Sharp, front-loaded fiscal or subsidy changes often trigger social protests that force policy reversals, leaving governments with neither fiscal credibility nor social stability.
Analytical Limits and Strategic Play
No single analytical framework or policy lever resolves the tension between sovereign solvency and social protection. Macro-financial models excel at tracking debt sustainability, interest rate sensitivity, and external balances, while distributional analyses capture household vulnerability and civic strain; reconciling them requires transparent trade-offs rather than slogans. Moreover, external multilateral financing cannot fix weak domestic tax administration, entrenched corruption, or geopolitical shocks outside a borrower’s control.
The strategic play for finance ministries, multilateral lenders, and civil society groups alike is to anchor fiscal and development planning in explicit distributional impact tracking before measures take effect. Finance officials and development banks should pair debt and macro stabilization metrics with pre-implementation assessments of how subsidy changes, tax shifts, and spending caps affect low-income households, care work, and employment, while sequencing adjustments gradually when external financing allows. Simultaneously, civil society coalitions will gain greater policy traction by pairing broad normative demands with concrete budget line items, revenue-raising options, and measurable social protection benchmarks that ministries can execute within real fiscal constraints.


