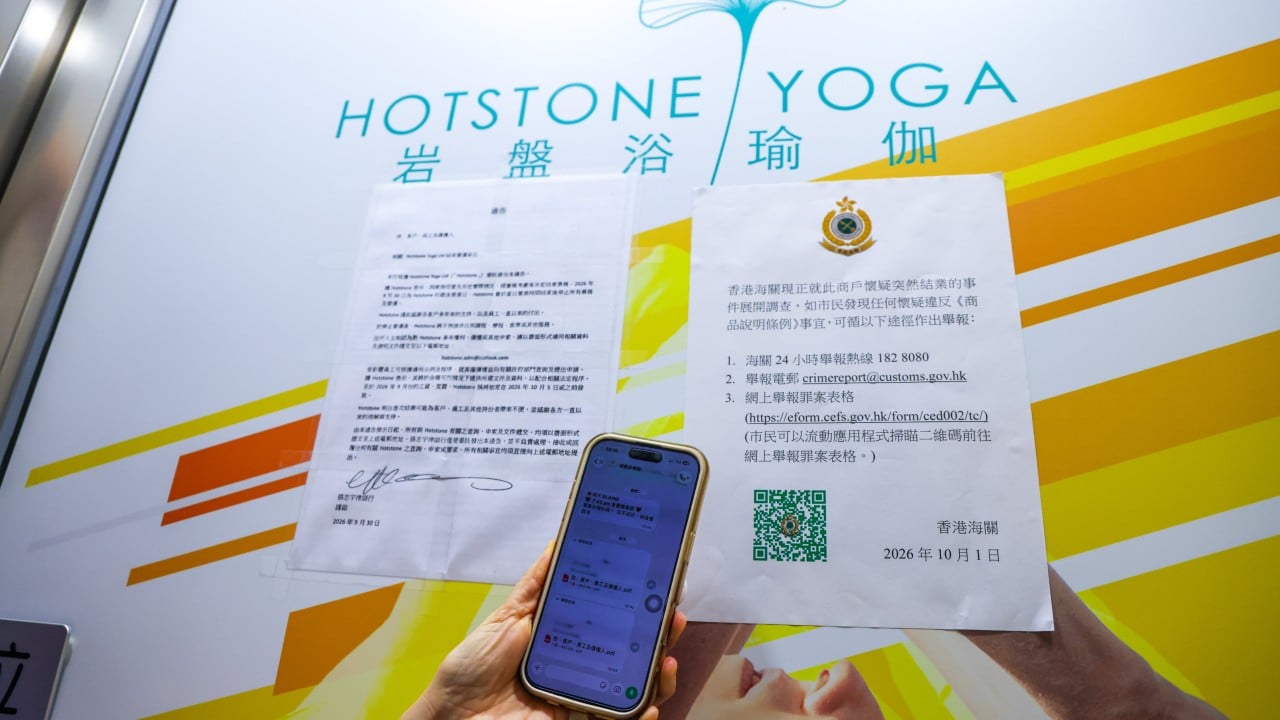
The sudden liquidation of subscription-based service chains exposes a critical structural flaw in modern retail economies: the monetization of unperformed services through upfront cash capture. When a commercial entity collapses overnight, leaving thousands of consumers holding unrendered contract credits and authorities scrambling to process thousands of formal grievances, the failure extends beyond the operational mismanagement of a single enterprise. It demonstrates a systemic vulnerability in consumer credit markets where cash flow is treated as recognized revenue before the underlying utility is delivered. Deconstructing this market failure requires examining the misalignment of incentives, the mechanics of liquidity depletion, and the regulatory architecture needed to neutralize consumer exposure in prepaid service sectors.
The Liquidity Trap of Upfront Capital Models
Service providers operating in high-fixed-cost sectors like fitness, wellness, and beauty frequently rely on long-term prepayment packages to solve immediate working capital constraints. By inducing consumers to purchase multi-month or multi-class bundles at a discounted unit rate, businesses manufacture an artificial liquidity spike. This capital inflow functions less like traditional earned revenue and more like an uncollateralized, interest-free loan extended by the consumer base to the corporate entity. Building on this idea, you can find more in: How One New Jersey Homebuyer Snagged a 575K House for 545K and Saved 350 Dollars Every Month.
[Consumer Capital Inflow] --> [Working Capital Pool] --> [Operational Overhead & Expansion]
                                                                     |
                                                           (Liquidity Exhaustion)
                                                                     v
[Abrupt Business Liquidation] <-- [Inability to Deliver Service] <-- [Insolvent Balance Sheet]
Under normal operational conditions, this model remains viable only if the velocity of new customer acquisition continuously outpaces the cost of servicing existing obligations. However, when macro-level demand contracts or operational overhead scales past sustainable unit economics, the balance sheet enters a terminal phase. Management is forced to choose between immediate insolvency or intensifying marketing efforts to secure fresh prepayments from new buyers to service legacy operational costs. This dynamic transforms the business into a structural operational loop dependent on continuous cash injections, accelerating the eventual scale of consumer losses when liquidation finally occurs.
Information Asymmetry and the Timing of Distress
A defining characteristic of corporate collapses in the service sector is the profound asymmetry of information between executive management and the consumer base. While internal financial statements reflect deteriorating cash reserves and mounting liabilities weeks or months before a shutdown, front-line staff are frequently kept uninformed to maintain daily sales momentum. Analysts at Harvard Business Review have shared their thoughts on this situation.
During the final operational window preceding the cessation of business, commercial staff continue aggressive sales campaigns for multi-class packages. This creates a severe ethical and economic hazard:
- The extraction of capital intensifies precisely when the probability of contract fulfillment approaches zero.
- Consumers evaluate purchase decisions based on historical brand equity rather than real-time balance sheet solvency.
- Legal entities often interpose corporate structures or asset shields that complicate direct recovery actions by unsecured creditors.
The concentration of losses among retail buyers highlights the absence of real-time credit visibility for consumers entering service contracts. Unlike financial instruments, where ratings agencies or mandatory disclosures signal default risk, lifestyle service contracts offer no transparent indicators of operational health.
The Regulatory Mechanics of Mandatory Cooling-Off Periods
Proposals for mandatory cooling-off periods and statutory escrow structures aim to alter the risk distribution between service providers and retail purchasers. A properly calibrated cooling-off framework introduces a friction window—typically a defined number of days post-purchase—during which a consumer retains the unilateral right to cancel a prepaid contract and demand a full or proportional refund.
Implementing this mechanism alters corporate behavior across three dimensions:
- Escrow Separation: Mandating that unearned prepayments be held in designated client accounts prevents firms from treating future service liabilities as immediate discretionary cash.
- Milestone Disbursement: Revenue is recognized incrementally only as the underlying service sessions are successfully delivered to the consumer, aligning cash flow with operational output.
- Deterrence of Ponzi-Style Growth: Eliminating the ability to use fresh prepayments to plug historical operational deficits forces businesses to maintain sustainable margins on actual service delivery.
Critics of such regulatory interventions often argue that mandatory cooling-off periods impose administrative burdens and restrict cash flow flexibility for emerging businesses. However, the recurring cycle of sudden closures and millions in stranded consumer funds indicates that unconstrained prepayment models externalize enterprise insolvency risk directly onto retail customers who lack the tools to audit corporate solvency.
Strategic Interventions for Market Stabilization
Preventing future market failures in high-prepayment service sectors requires shifting from reactive penal enforcement to proactive structural safeguards. Lawmakers and consumer protection agencies must establish statutory limits on the maximum duration and financial volume of single-contract prepayments permitted within designated high-risk industries.
Concurrently, enforcement agencies must target the systemic misuse of corporate entities where directors shield themselves behind layered corporate shells while continuing to accept cash for services they know cannot be rendered. By tying director liability directly to the continued solicitation of prepayments during insolvency phases, regulators can shift the operational calculus away from high-risk cash harvesting and toward sustainable, subscription-based or pay-as-you-go service delivery models. The structural integrity of service markets depends entirely on eliminating the arbitrage opportunity of trading unperformed promises for immediate liquidity.