When a generational asset enters bankruptcy while facing intensifying operational liabilities, the asset's underlying enterprise value undergoes a rapid structural collapse. The recent legal and financial distress surrounding Camp Mystic—a historic summer camp property facing bankruptcy proceedings amid mounting legal challenges—provides a textbook case study in how unmitigated operational risk bleeds directly into real estate liquidation value. In distressed asset scenarios, market participants often mistake emotional heritage for equity value. This analysis deconstructs the mechanics of the Camp Mystic bankruptcy, isolating the intersection of liability-driven insolvency, real estate monetization, and enterprise value destruction.
The Three Drivers of Distressed Camp Asset Valuation
Evaluating a legacy recreational property under bankruptcy protection requires stripping away sentiment and examining three rigid valuation variables: contingent liability overhang, deferred maintenance drag, and land-use monetization friction.
The primary driver of distress in this scenario is the accumulation of contingent liabilities. When legal challenges multiply, potential buyers face an unpredictable horizon of defense costs, potential judgments, and reputational risk. In corporate finance, an unquantified liability acts as a heavy discount factor on enterprise value. Prospective buyers of camp properties typically underwrite the asset based on normalized EBITDA multiplied by a hospitality sector multiple. However, when active litigation threatens the going-concern status of the operating entity, the business model breaks. The buyer cannot underwrite a predictable cash flow stream when the core operational brand is tethered to legal exposure.
The second variable involves deferred capital expenditures. Legacy properties often operate on decades-old infrastructure. While campers experience rustic charm, financial analysts perceive hidden liabilities in aging wastewater treatment systems, non-compliant electrical grids, and outdated dormitory facilities. When an operating entity enters Chapter 11 or Chapter 7 bankruptcy, deferred maintenance items transform from operational inconveniences into mandatory capital outlays required by municipal code enforcement and environmental regulators. A court-ordered sale forces these hidden costs into the open, depressing net recovery proceeds for creditors.
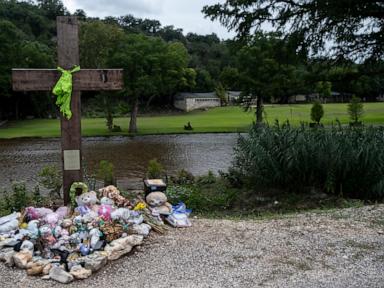
The third variable is land-use friction. A riverfront camp property sitting on prime acreage in the Texas Hill Country or similar recreational corridors possesses high alternative-use value. However, translating a youth camp into luxury residential lots, private retreat compounds, or boutique hospitality ventures encounters severe friction. Local zoning laws, environmental conservation easements, riparian rights governing water extraction from adjacent rivers, and historical preservation pushes create a lengthy bureaucratic bottleneck. The time value of money penalizes any buyer who must spend years navigating zoning boards before generating yield from the land.
The Cost Function of Legal Insolvency
The transition from operational disputes to formal bankruptcy introduces an aggressive administrative cost function that rapidly erodes asset value. Understanding this erosion requires examining the mechanics of judicial sales.
When a property is listed for sale within a bankruptcy proceeding, it typically follows a court-supervised process governed by Section 363 of the Bankruptcy Code. This mechanism is designed to maximize recovery through competitive bidding, but it introduces acute friction:
- Professional Fees Burn Rate: Legal counsel, restructuring officers, and court-appointed trustees siphon liquidity from the estate on a monthly retainer basis. In smaller recreational real estate bankruptcies, professional fees can consume a disproportionate percentage of the gross liquidation value.
- Operational Stagnation: Uncertainty freezes forward bookings. Parents hesitate to enroll children in a camp facing court supervision and ownership changes. The loss of advance tuition deposits—which typically provide seasonal businesses with zero-cost working capital during the off-season—starves the operating entity of cash flow.
- Stigma Discount: The market brands distressed assets with a psychological discount. Institutional buyers and private equity syndicates know the seller is under duress, weakening the debtor's negotiating leverage and inviting low-ball stalking-horse bids.
This creates a self-reinforcing downward spiral. Legal pressure damages enrollment, lost enrollment eliminates working capital, cash depletion forces bankruptcy filing, and bankruptcy triggers administrative fees that consume the remaining equity cushion.
Asset Disaggregation and Real Estate Monetization Pathways
To understand the likely outcome of the Camp Mystic property sale, market analysts must disaggregate the asset base into its constituent components. A unified camp enterprise is rarely sold as a single operating unit during deep insolvency; instead, it is parsed out to maximize recovery for secured creditors.
Real estate monetization typically follows one of three structural pathways in these scenarios:
The first pathway is a whole-property acquisition by a strategic buyer in the youth camping sector. This preserves the historical continuity of the brand and utilizes existing improvements with minimal conversion costs. However, this outcome depends entirely on whether the legal liabilities are fully quarantined from the buyer. If the legal exposure attaches to the land or the corporate entity, strategic buyers in the youth space will walk away due to fiduciary risk management.
The second pathway is private equity consolidation into alternative high-end hospitality or wellness real estate. The physical footprint of traditional camps—cabins, dining halls, waterfront access, and open acreage—aligns well with the booming market for corporate retreats, luxury glamping resorts, and private family compounds. Yet, converting a camp to commercial hospitality requires massive zoning variances and significant capital investment to upgrade infrastructure to modern commercial building codes.
The third pathway is subdivision and conservation sale. If the enterprise value drops to zero, the creditors' primary recourse is the underlying land. Waterfront acreage along major recreational rivers commands strong baseline land values per acre. Portions of the property may be sold off for residential development, while sensitive riparian zones might be placed into conservation easements to generate tax credits or offset municipal requirements.
Strategic Outlook and Market Forecast
The trajectory of the Camp Mystic property sale illustrates the harsh reality of asset management under legal duress. Sentiment, history, and generational goodwill hold zero weight on a balance sheet. When legal exposure disrupts cash flow generation, the enterprise value evaporates, leaving only the salvage value of the underlying real estate and physical improvements.
Future market value for properties of this class will hinge on the total containment of legacy liabilities. If the bankruptcy court successfully severs historical legal exposure from the real estate title, asset-backed investors will step in to redevelop the acreage into higher-yielding alternative formats. If liabilities cling to the land, the property faces prolonged litigation, deep valuation haircuts, and an eventual breakup sale that permanently erases its operational legacy. The strategic imperative for any distressed recreational asset is immediate liability restructuring before judicial intervention preempts private optionality.